Ontario Home Insurance: What's Covered (and What Isn't)
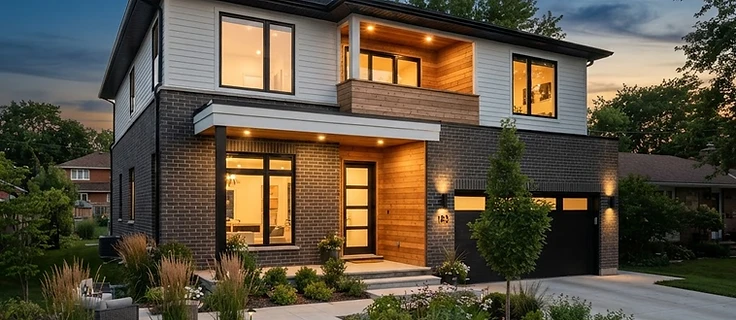
Most policies look alike until you have a claim. Here's a clear breakdown of what an Ontario home insurance policy covers, the common gaps, and how to read your limits.
A standard Ontario home insurance policy protects your dwelling, your belongings, and your personal liability, but two policies that look identical on price can behave very differently at claim time. Knowing what is built in, what is optional, and what is silently excluded is the difference between a smooth claim and an expensive surprise.
In short
- A standard Ontario home policy covers the dwelling, your contents, additional living expenses, personal liability, and detached structures.
- Sewer back-up and overland water are almost always optional endorsements, not base coverage.
- Replacement cost pays to rebuild without deducting depreciation, while actual cash value deducts it and pays less.
- Vacancy beyond about 30 days can suspend coverage unless you notify your insurer.
Shop 17+ insurers in one go.
Get a free quote and a dedicated Ontario broker who explains every option and stays with you to renewal.
Start your quoteWhat is typically covered
- Dwelling, the physical structure of your home against insured perils such as fire, lightning, wind, hail, smoke, and certain water damage.
- Personal property (contents), your furniture, electronics, clothing, and appliances, usually insured at actual cash value or replacement cost.
- Additional living expenses, hotel, meals, and storage if your home is uninhabitable after a covered loss.
- Personal liability, protection if someone is injured on your property or you accidentally damage someone else's, with limits typically starting at $1 million and rising to $2 million or more.
- Detached structures, garages, sheds, and fences on the property.
Common gaps people miss
- Overland water and sewer back-up. Water entering from the sewer line, a river, or heavy rainfall is almost always an optional endorsement, not base coverage. In older Ontario neighbourhoods with clay sewer lines, sewer back-up is close to essential.
- High-value items. Jewellery, art, collectibles, and electronics are capped, often at $2,000 to $5,000 per item. Schedule them separately so a loss pays replacement cost.
- Home business activity. Running a business from home can void parts of a personal policy. A home-business endorsement or a commercial policy keeps both sides covered.
- Vacancy. Leaving a home unoccupied for more than about 30 days can suspend coverage unless you notify the insurer first.
Replacement cost vs. actual cash value
Replacement cost rebuilds or replaces your home and belongings without deducting depreciation. Actual cash value deducts depreciation and pays less. Always confirm which basis your dwelling and contents are on, it is the single biggest surprise at claim time. Most well-built policies insure the dwelling to replacement cost and offer contents on either basis.
How Ontario home insurance is priced
Premiums reflect the rebuild cost of the home, not its market value, the age and construction of the building, your claims history, your proximity to water and a fire hydrant, the deductible you choose, and the endorsements you add. A centre such as Toronto or Mississauga prices differently from Kingston or London, and older housing stock in Hamilton or Brantford can carry higher water-loss exposure than new build. A broker models replacement cost honestly and adds only the endorsements that actually matter for your property.
How to read your limits before you need them
A few minutes with a licensed broker surfaces the gaps above before they cost you. We review your dwelling limit against rebuild cost, schedule high-value items, confirm water coverage, and quote home insurance, condo insurance, and tenant insurance side by side so you choose with full transparency.
Where Truly Insurance insures across Ontario
Truly Insurance is an Ontario insurance brokerage, and our team of licensed insurance brokers is authorized to arrange coverage anywhere in the province. Our home office is in Kitchener, at 22 Water St S Ste 100, and our brokers work with clients across the Waterloo Region cities of Waterloo, Cambridge, and Guelph, the Southwestern Ontario corridor including London, Brantford, and Stratford, the entire Greater Toronto Area from Toronto and Mississauga to Brampton and Markham, Eastern Ontario including Ottawa and Kingston, and Northern Ontario including Greater Sudbury and Thunder Bay.
You do not have to live near our Kitchener office to work with us. Every Ontario policy is arranged by a named broker who works with you by phone, email, and video, and our team can quote, bind, and service coverage for any address in the province. Find your city or call (519) 800-4770 and a licensed Ontario broker will reach out the same day.
Frequently asked questions
What does Ontario home insurance cover?+
A standard policy covers the dwelling, your personal contents, additional living expenses if the home is uninhabitable, personal liability, and detached structures. Water damage from sewer back-up or overland flooding is usually optional and must be added as an endorsement.
How much is home insurance in Ontario?+
A typical Ontario home policy runs from roughly $1,000 to $2,500 a year depending on rebuild cost, age, location, limits, and endorsements. Condo and tenant policies cost less because the building envelope is covered by the corporation or landlord.
Is sewer back-up coverage included in Ontario home insurance?+
No. Sewer back-up is an optional endorsement in almost every Ontario policy. In older neighbourhoods with clay sewer lines it is strongly recommended, and it is separate from overland flood cover.
What is the difference between replacement cost and actual cash value?+
Replacement cost pays to rebuild or replace without deducting depreciation. Actual cash value deducts depreciation and pays less. Confirm which basis your dwelling and contents are on before a claim.
Does home insurance cover a home business?+
Usually not by default. Running a business from home can void parts of a personal policy. A home-business endorsement or a separate commercial policy keeps both sides covered.
What happens if my home is vacant?+
Most policies suspend or narrow some coverage after about 30 consecutive days of unbroken vacancy unless you notify the insurer. Tell your broker the day the home goes empty and the window can be extended.
Disclaimer: This article is for general information only and is not financial or insurance advice. Rates, coverage, and eligibility vary by individual circumstances, insurer, and region. Always contact a licensed insurance broker for guidance specific to your situation.
Keep reading

 Guides
Should You Make a Claim or Pay Out of Pocket? How a Claim Affects Your Premium
Paying for a small loss yourself can cost less than the premium increase a claim triggers, but only when the damage is genuinely small and nobody is hurt. Here is how fault, Ontario's minor at-fault accident rule, accident forgiveness, and home claims actually move your premium.
Read article
 Auto Insurance
Car Insurance for Young Drivers in Ontario: What Actually Sets the Price
A young driver's Ontario premium is built from age, years licensed, driving record, vehicle, address, and coverage, and age is a legal rating factor in this province. Here is what each licence level means for a policy, the discounts worth asking about, and the small disclosure mistakes that cost the most.
Read article
 Auto Insurance
Winter Tire Insurance Discounts in Ontario: What Drivers Need to Know
Every Ontario auto insurer has to offer a winter tire discount, but the percentage, the qualifying window, and the proof are decided company by company. Here is how the discount actually works, which tires count, and what happens if the season does not go to plan.
Read article